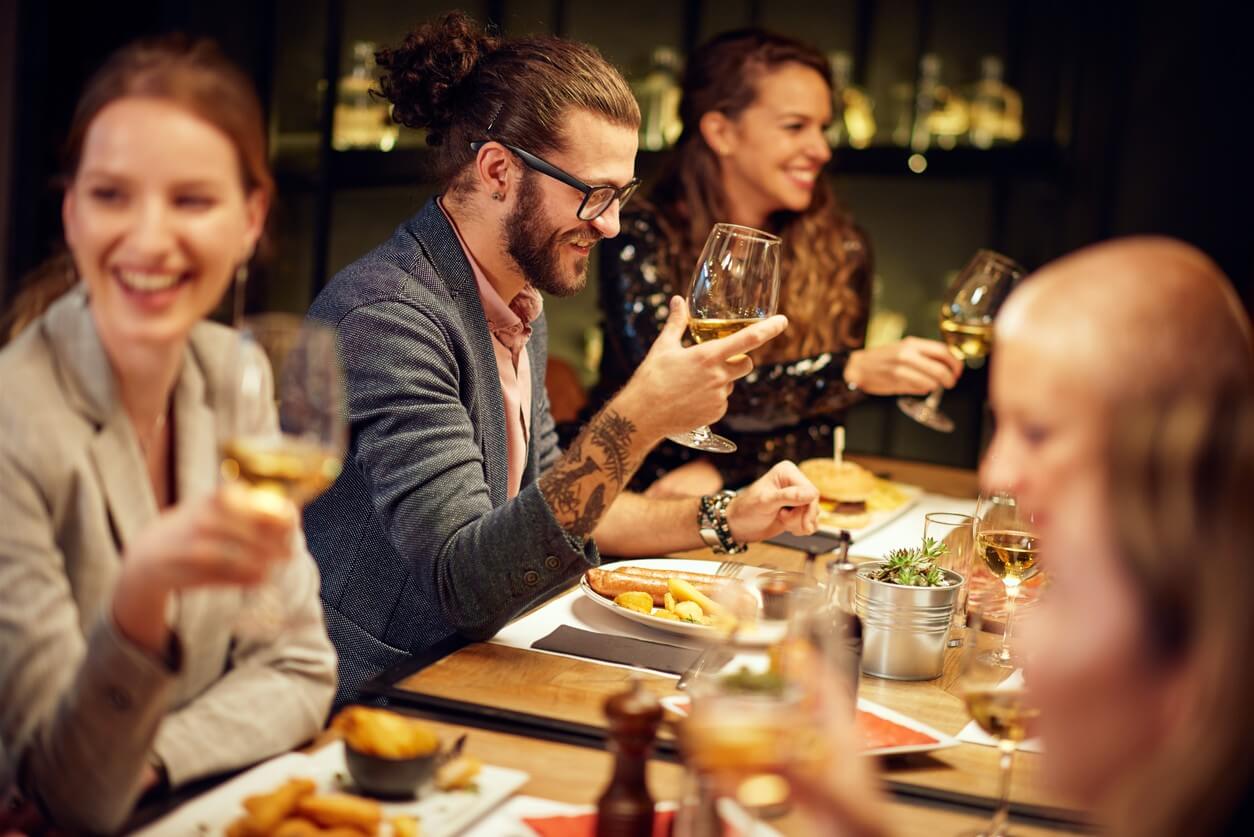
An everyday occurrence across the business landscape in Australia is the practice of taking both existing and
potential clients out for a meal
to cement the business relationship, with the cost of this meal often covered by one party.
Equally, business owners commonly reward by taking high performing employees out for lunch and covering the cost.
The provision of meal entertainment benefits can be a taxation minefield. If you have questions regarding your business practices
and how you reward your employees please contact us on (03) 5911 7000 or send us an email.
Granting employees’ access to company cars is treated by the ATO as a ‘non-cash benefit’, more commonly referred to as a fringe benefit.
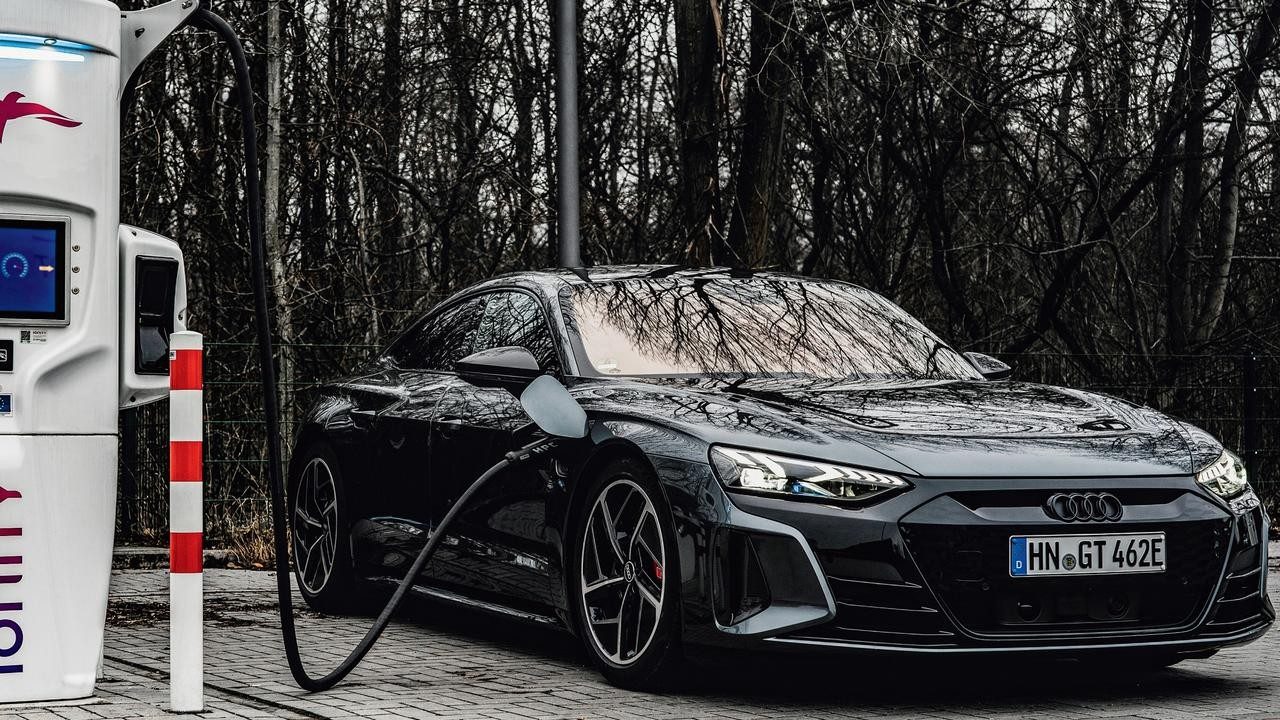
New legislation before Parliament, if enacted, will make zero or low emission vehicles FBT-free. We explore who can access the concession and how.
An everyday occurrence across the business landscape in Australia is the practice of taking both existing and potential clients out for a meal to cement the business relationship, with the cost of this meal often covered by one party.
The ATO has signalled that there will be an increased focus on FBT this year. Given the ever-improving tools at the ATO’s disposal, in conjunction with the government’s need to raise additional revenues, it is important that employers ensure they remain compliant with their FBT requirements.
The ATO will stop accepting direct credit card payments from 1 December 2026, requiring businesses and individuals to switch to alternative payment methods such as debit card, BPAY, EFT or bank account direct debit. While the change affects only a small percentage of taxpayers, businesses that rely on credit cards to manage cash flow or fund ATO payment plans should act now to update arrangements, avoid missed payments and prepare for the cash flow impact of having tax obligations funded from available business funds.
Hiring entertainers, promotional staff or event contractors for your Christmas function could create superannuation obligations you didn't expect.